Expert Guide to Fixed-Rate and Adjustable-Rate Mortgages (ARMs) in Greenwood Village, CO

Whether you are purchasing your first home, upgrading to your dream house, or looking to refinance your current property in Greenwood Village, Colorado, choosing the right mortgage program is one of the most critical financial decisions you will make. The two most common paths for homebuyers are Fixed-Rate Mortgages and Adjustable-Rate Mortgages (ARMs). Each loan type offers distinct advantages, and understanding how they align with your financial goals, timeline, and the local Denver Metro real estate market is essential.

Primary Residential Mortgage, Inc. logo

Understanding Fixed-Rate Mortgages

A Fixed-Rate Mortgage is the most traditional and popular home financing option in the United States. As the name suggests, the interest rate on this type of loan remains exactly the same for the entire life of the loan. This means your monthly principal and interest payment will never change, regardless of how market interest rates fluctuate over time.

Common Fixed-Rate Terms

  • 30-Year Fixed-Rate Mortgage: The industry standard. By spreading the loan balance over 30 years, you benefit from the lowest possible monthly payments, making homeownership more accessible and leaving you with more disposable income each month.
  • 15-Year Fixed-Rate Mortgage: This option comes with higher monthly payments compared to a 30-year loan, but it allows you to build home equity much faster and saves you tens, or even hundreds, of thousands of dollars in total interest over the life of the loan.
  • 20-Year and 10-Year Fixed-Rate Mortgages: These are excellent middle-ground options for borrowers looking to balance manageable monthly payments with accelerated equity growth.

The Benefits of a Fixed-Rate Mortgage

Opting for a fixed-rate home loan provides several distinct advantages, particularly for long-term homeowners in Greenwood Village:

  • Ultimate Predictability: Budgeting is incredibly simple. Because your principal and interest payment is locked in, you never have to worry about payment shock caused by rising interest rates. (Note: Your total monthly payment may still fluctuate slightly due to changes in property taxes or homeowners insurance premiums).
  • Protection Against Inflation: If national interest rates skyrocket, your fixed-rate mortgage remains untouched. You are effectively insulated from economic volatility.
  • Simplicity: Fixed-rate loans are straightforward and easy to understand. There are no complex adjustment caps, margins, or index rates to track.

When is a Fixed-Rate Mortgage the Best Choice?

A fixed-rate mortgage is highly recommended if you plan to stay in your Greenwood Village home for a long time—typically seven to ten years or more. It is also the ideal choice if you are on a fixed income, value financial stability, or are buying a home during a period of historically low interest rates.

Understanding Adjustable-Rate Mortgages (ARMs)

An Adjustable-Rate Mortgage (ARM) is a home loan with an interest rate that can change periodically. This means that your monthly payments can go up or down based on broader financial market trends. However, modern ARMs are actually “hybrid” loans, meaning they begin with a fixed interest rate for an initial period before transitioning into an adjustable rate.

How Hybrid ARMs Work

ARMs are typically expressed as two numbers, such as 5/1, 7/1, or 10/1.

  • The First Number (The Fixed Period): This represents the number of years your initial interest rate is fixed. For example, in a 5/1 ARM, your rate will not change for the first five years.
  • The Second Number (The Adjustment Period): This represents how often the rate can adjust after the initial fixed period ends. In a 5/1 ARM, the “1” means the rate can adjust once every year after the initial five-year period. (Note: Some modern ARMs are structured as 5/6, meaning the rate adjusts every 6 months after the initial 5-year period).

Understanding ARM Caps

To protect borrowers from extreme payment shock, ARMs come with built-in safety nets known as “caps.” These caps limit exactly how much your interest rate can increase:

  • Initial Adjustment Cap: The maximum amount the rate can increase the very first time it adjusts.
  • Subsequent (Periodic) Adjustment Cap: The maximum amount the rate can increase during any subsequent adjustment period.
  • Lifetime Cap: The absolute maximum interest rate you can be charged over the entire life of the loan, regardless of how high market index rates climb.

The Benefits of an Adjustable-Rate Mortgage
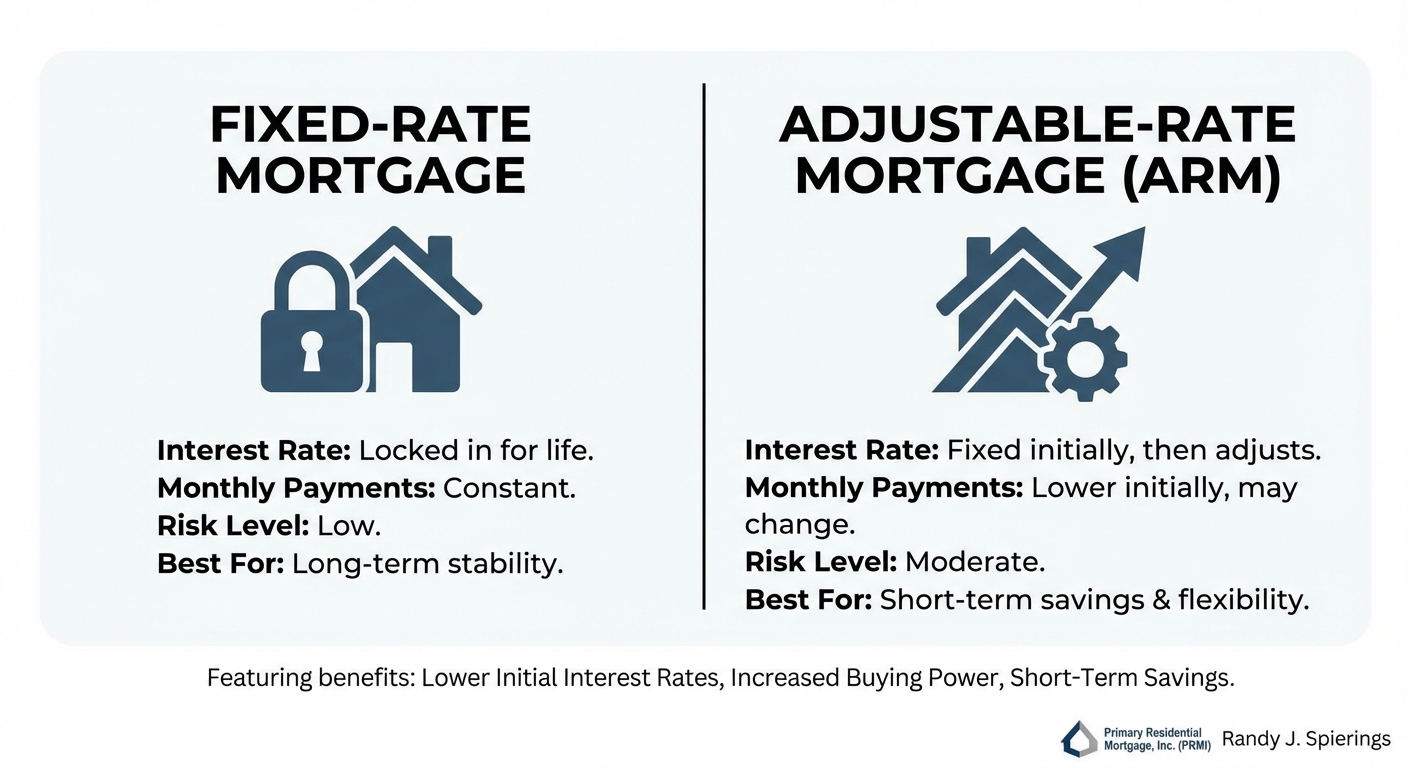
Create a professional section image for this content. Context (from section below): Lower Initial In

  • Lower Initial Interest Rates: ARMs almost always feature a lower starting interest rate compared to 30-year fixed-rate mortgages. This translates to significantly lower monthly payments during the introductory period.
  • Increased Buying Power: Because the initial rate is lower, you may qualify for a larger loan amount, allowing you to afford a more expensive home in a competitive market like Greenwood Village or the broader Denver Metro area.
  • Short-Term Savings: If you plan to sell your home or refinance your mortgage before the initial fixed period ends, you can take advantage of the lower introductory rate without ever facing an upward rate adjustment.

When is an ARM the Best Choice?

An ARM is an excellent financial tool if you are a corporate relocation buyer, military member, or growing family who plans to move or upgrade within 5 to 10 years. It is also a smart strategy if you anticipate a significant increase in your future income, or if you plan to aggressively pay down your principal balance during the low-rate introductory period.

Key Benefits of First-Time Homebuyer Programs

  • Lower Down Payments: Many programs allow you to buy a home with as little as 0% to 3.5% down, significantly reducing your out-of-pocket expenses.
  • Flexible Credit Requirements: First-time buyer loans often have more lenient credit score minimums compared to traditional jumbo or standard conventional loans.
  • Down Payment Assistance (DPA): Access to grants and secondary loans that can cover your down payment and closing costs.
  • Reduced Mortgage Insurance: Certain programs offer discounted private mortgage insurance (PMI) rates, lowering your monthly payment.
  • Educational Resources: Many state-sponsored programs provide homebuyer education classes to prepare you for the responsibilities of homeownership.


Comparing Your Options: Fixed-Rate vs. ARM

FeatureFixed-Rate MortgageAdjustable-Rate Mortgage (ARM)
Interest RateLocked in for the life of the loan.Fixed for an initial period, then adjusts periodically based on the market.
Monthly PaymentsPrincipal and interest remain constant.Lower initially, but can increase or decrease after the fixed period.
Initial Rate LevelGenerally higher than the initial rate of an ARM.Generally lower than a 30-year fixed-rate mortgage.
Best Suited For…Long-term homeowners seeking stability and predictable budgeting.Short-term homeowners, or borrowers seeking immediate cash flow relief.
Risk LevelLow risk. You are protected from rising market interest rates.Moderate risk. Payments may increase if market rates rise after the fixed period.

Why Choose Randy J. Spierings as Your Mortgage Broker in Greenwood Village?

Navigating the complex world of home financing requires a trusted local expert. Randy J. Spierings, representing Primary Residential Mortgage, Inc. (PRMI), offers unparalleled service, deep local market knowledge, and access to highly competitive mortgage rates in Colorado.

  • Local Market Expertise: Real estate in Greenwood Village and the Denver Metro area moves fast. Randy understands local property values, tax structures, and community nuances, ensuring your pre-approval holds weight with local listing agents.
  • Customized Financial Strategies: Randy doesn’t believe in a one-size-fits-all approach. He takes the time to understand your short-term needs and long-term financial goals before recommending a Fixed-Rate or ARM product.
  • Seamless, Transparent Process: From the initial application to the closing table, Randy and the PRMI team prioritize clear communication. You will never be left wondering about the status of your loan.
  • Comprehensive Loan Options: Beyond Fixed and ARM loans, Randy offers a full suite of mortgage products including FHA loans, VA loans, USDA loans, Jumbo loans, and refinancing options.

Our Simple Mortgage Process

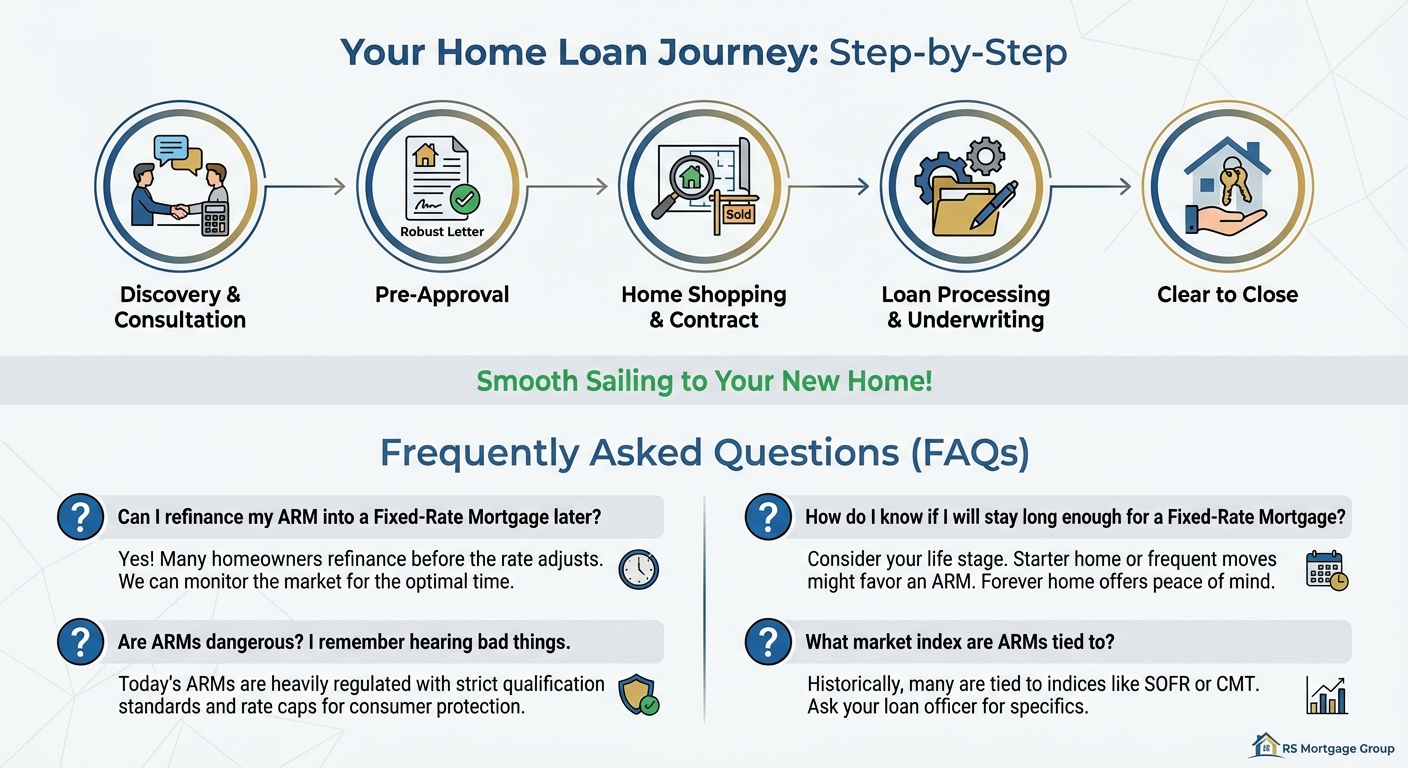
Create a professional section image for this content. Context (from section below): Discovery & Cons

  1. Discovery & Consultation: We start with a brief conversation to discuss your homeownership goals, budget, and financial background. We will weigh the pros and cons of Fixed-Rate vs. ARM loans specifically for your situation.
  2. Pre-Approval: We gather your financial documentation (income, assets, credit history) to issue a robust pre-approval letter. This shows Greenwood Village home sellers that you are a serious, qualified buyer.
  3. Home Shopping & Contract: You work with your real estate agent to find your perfect home. Once your offer is accepted, you send the purchase contract to our team.
  4. Loan Processing & Underwriting: Randy’s team handles the heavy lifting. We order the property appraisal, verify all documentation, and submit your file to underwriting for final approval.
  5. Clear to Close: Once underwriting approves your loan, we finalize the numbers, schedule your closing date, and hand you the keys to your new home!

Frequently Asked Questions

Can I refinance my Adjustable-Rate Mortgage into a Fixed-Rate Mortgage later?

Yes, absolutely! Many homeowners start with an ARM to take advantage of the low initial interest rate. Before the fixed period expires and the rate begins to adjust, they choose to refinance their loan into a traditional 30-year or 15-year Fixed-Rate Mortgage. Randy Spierings can monitor the market for you and advise you on the optimal time to refinance.

The ARMs offered today are vastly different from the high-risk loans seen prior to the 2008 housing crisis. Today’s ARMs are heavily regulated and feature strict qualification standards. Borrowers must qualify for the loan based on the maximum possible adjusted rate, not just the low introductory rate. Furthermore, modern rate caps strictly limit how much your payment can increase, providing a strong layer of consumer protection.

While no one can predict the future with 100% accuracy, it helps to evaluate your current life stage. Are you buying a “starter home” that you will likely outgrow if you have children? Are you in an industry that requires frequent relocation? If the answer is yes, an ARM might be the mathematical winner. If you are buying your “forever home” near great Greenwood Village schools or preparing to retire in place, a Fixed-Rate loan offers unmatched peace of mind.

Historically, many ARMs were tied to the LIBOR index. Today, most new Adjustable-Rate Mortgages are tied to the Secured Overnight Financing Rate (SOFR) or the Constant Maturity Treasury (CMT) index. During your consultation, Randy will clearly explain the specific index and margin associated with your loan quote.

Estimate Your Monthly Payments

Understanding your potential mortgage payments is a crucial step in the home-buying process. Our easy-to-use Mortgage Calculator helps you estimate your monthly payments, so you can plan your finances with confidence. Simply enter your loan details and let our calculator do the rest.

mortgage
Primary Residential Mortgage, Inc. logo

PRMI NMLS 3094. PRMI is an Equal Housing Lender. Credit and collateral are subject to approval. Terms and conditions apply. Programs, rates, terms and conditions are subject to change and are subject to borrower(s) qualification. This is not a commitment to lend. The content in this website has not been approved, reviewed, sponsored or endorsed by any department or government agency.

Equal Housing Lender Logo
Customer satisfaction badge