Expert Mortgage Refinancing Options in Greenwood Village, CO

Are you looking to lower your monthly mortgage payments, consolidate high-interest debt, or tap into your home’s equity for a major renovation? As a homeowner in Greenwood Village, Colorado, your property is one of your most valuable financial assets. Navigating the current mortgage market requires a strategic approach, and choosing the right refinancing option can save you thousands of dollars over the life of your loan.

Primary Residential Mortgage, Inc. logo

Why Consider Refinancing Your Colorado Home?

Refinancing simply means replacing your current mortgage with a new one that offers better terms, a lower interest rate, or different features that align with your current financial situation. Because the Colorado real estate market has seen significant appreciation over the last several years, many homeowners in Greenwood Village are sitting on substantial equity. Here are the top reasons why homeowners choose to refinance:

  • Lowering the Interest Rate: Securing a lower interest rate is the most common reason to refinance. Even a fraction of a percentage point reduction can significantly decrease your monthly payment and save you tens of thousands of dollars in interest over the life of the loan.
  • Reducing the Loan Term: If your financial situation has improved, you might choose to refinance from a 30-year mortgage to a 15-year mortgage. While your monthly payment may be slightly higher, you will build equity much faster and save a massive amount on interest.
  • Transitioning from an ARM to a Fixed-Rate Mortgage: Adjustable-Rate Mortgages (ARMs) often start with low introductory rates that eventually adjust to market conditions. Refinancing into a fixed-rate mortgage provides predictable, stable monthly payments, protecting you from future interest rate hikes.
  • Cashing Out Home Equity: A cash-out refinance allows you to leverage the equity you have built in your home. You can use these funds for home improvements, college tuition, medical expenses, or starting a business.
  • Consolidating Debt: By rolling high-interest credit card debt, auto loans, or personal loans into your mortgage, you can take advantage of a much lower overall interest rate and simplify your finances into one manageable monthly payment.
  • Removing Private Mortgage Insurance (PMI): If you originally purchased your home with less than a 20% down payment, you are likely paying PMI. If your home’s value has increased or you have paid down your balance enough to reach 20% equity, refinancing can eliminate this costly monthly fee.

Comprehensive Refinancing Options Tailored to Your Goals

A first-time homebuyer program is a specialized mortgage loan, grant, or financial assistance initiative designed to help individuals purchase their first primary residence. These programs are typically offered by federal agencies, state housing finance authorities, and private lenders.

It is important to note that in the mortgage industry, a “first-time homebuyer” is generally defined as someone who has not owned a principal residence in the past three years. If you owned a home four years ago but have been renting since, you may still qualify for these incredible benefits!

Comprehensive Refinancing Options Tailored to Your Goals

There is no “one-size-fits-all” approach to mortgage refinancing. Randy J. Spierings takes the time to analyze your unique financial profile and long-term objectives to recommend the best loan product. Below are the primary refinancing options available to Greenwood Village homeowners.

1. Rate-and-Term Refinance

A rate-and-term refinance is the most traditional type of refinancing. As the name suggests, it allows you to change the interest rate, the loan term, or both, without advancing any new money (other than closing costs, which can often be rolled into the new loan).

Best for: Homeowners looking to lower their monthly payments, pay off their home faster by switching to a shorter term, or switch from an adjustable rate to a fixed rate.

2. Cash-Out Refinance

A cash-out refinance replaces your existing mortgage with a new loan for more than you currently owe. You receive the difference in cash at closing. Because homes in Greenwood Village and the greater Denver area have appreciated significantly, many homeowners have untapped wealth sitting in their property.

Best for: Homeowners who need a large sum of money for high-ROI home renovations, consolidating high-interest debt, or funding major life events. The interest rates on a cash-out refinance are typically much lower than personal loans or credit cards.

3. FHA Streamline Refinance

If you currently have a mortgage backed by the Federal Housing Administration (FHA), you may be eligible for an FHA Streamline Refinance. This program is designed to be fast and cost-effective. It requires less documentation, often does not require a new home appraisal, and has lower credit requirements.

Best for: Current FHA loan holders who want to quickly lower their interest rate and monthly payments with minimal paperwork and closing costs.

4. VA Interest Rate Reduction Refinance Loan (IRRRL)

Also known as a VA Streamline Refinance, the IRRRL is an exclusive benefit for veterans, active-duty military members, and eligible surviving spouses who already have a VA loan. Like the FHA Streamline, this option requires no new appraisal, no income verification, and minimal paperwork.

Best for: Veterans and military families with existing VA loans who want to take advantage of lower market interest rates quickly and easily.

5. VA Cash-Out Refinance

Unlike the IRRRL, the VA Cash-Out Refinance allows eligible veterans to extract up to 100% of their home’s equity (depending on lender guidelines) as cash. You do not need to currently have a VA loan to utilize this option; you can refinance a conventional or FHA loan into a VA Cash-Out loan to take advantage of the VA’s favorable terms.

Best for: Eligible military personnel and veterans who want to consolidate debt or make home improvements while utilizing their hard-earned VA loan benefits.

6. Jumbo Loan Refinance

Greenwood Village is known for its luxury real estate and higher-than-average home prices. If your mortgage balance exceeds the conforming loan limits set by the Federal Housing Finance Agency (FHFA), you will need a Jumbo Refinance. Randy Spierings specializes in high-net-worth mortgage solutions and can secure competitive rates on jumbo refinancing.

Best for: Homeowners with luxury properties or high mortgage balances who want to lower their rates, change their terms, or extract cash from their substantial equity.


At-a-Glance: Comparing Refinancing Options

To help you understand which path might be right for you, review this quick comparison of our most popular refinancing programs:

Refinance TypePrimary BenefitAppraisal Required?Credit/Income Verification?Best Use Case
Rate-and-TermLower rate or shorter termUsuallyYesReducing monthly payments or paying off the home faster.
Cash-OutAccess home equity as cashYesYesHome improvements, debt consolidation, large expenses.
FHA StreamlineFast rate reductionNoMinimalCurrent FHA borrowers wanting a lower payment quickly.
VA IRRRLFast rate reduction for VetsNoMinimalCurrent VA borrowers wanting a lower payment quickly.
Jumbo RefinanceRefinancing high-balance loansYes (Sometimes two)Yes (Strict)Luxury homeowners looking to optimize their mortgage terms.

The Refinancing Process with Randy J. Spierings

The thought of refinancing can feel overwhelming, but it doesn’t have to be. By partnering with Randy Spierings at Primary Residential Mortgage, Inc., you are guaranteed a streamlined, transparent, and communicative process from start to finish. Here is what you can expect when you choose to refinance your Greenwood Village home with us:

Step 1: The Initial Consultation and Goal Assessment

Every successful refinance begins with a conversation. Randy will discuss your short-term and long-term financial goals. Are you looking to maximize monthly cash flow? Do you need capital to renovate your kitchen? Are you trying to pay off your home before retirement? Understanding your “why” allows Randy to recommend the perfect mortgage product.

Step 2: Application and Pre-Approval

Once you have selected a refinancing strategy, you will complete a secure application. You will need to provide standard financial documentation, including recent pay stubs, W-2s, tax returns, and bank statements. Randy and his team will review your credit profile and home equity position to provide a clear path forward.

Step 3: Locking in Your Interest Rate

Mortgage rates fluctuate daily based on economic indicators. With his deep understanding of the market, Randy will advise you on the optimal time to lock in your interest rate, ensuring you are protected against sudden market increases while securing the best possible terms.

Step 4: The Home Appraisal (If Applicable)
Create a professional section image for this content. Context (from section below): Step 5: Underwri

Step 5: Underwriting and Approval

The PRMI underwriting team will review your complete file to ensure it meets all loan guidelines. Randy’s proactive approach means that potential issues are addressed early in the process, resulting in a smooth and efficient underwriting phase. If any additional documentation is needed, Randy’s team will communicate with you promptly.

Step 6: Closing and Funding

Is Now the Right Time to Refinance in Greenwood Village?

Timing the market perfectly is nearly impossible, but waiting too long can cost you opportunities. You should strongly consider reaching out to Randy Spierings if you meet any of the following criteria:

  • Current mortgage rates are at least 0.5% to 1% lower than your existing rate.
  • Your credit score has significantly improved since you originally purchased your home.
  • You have accumulated a large amount of high-interest consumer debt (credit cards, personal loans) that is straining your monthly budget.
  • Your home’s value has skyrocketed, pushing your equity well above the 20% threshold, meaning you can drop your PMI.
  • You are currently in an Adjustable-Rate Mortgage (ARM) that is about to reset to a higher rate.

Common Refinancing Mistakes to Avoid

Create a professional section image for this content. Context (from section below): Focusing Only on

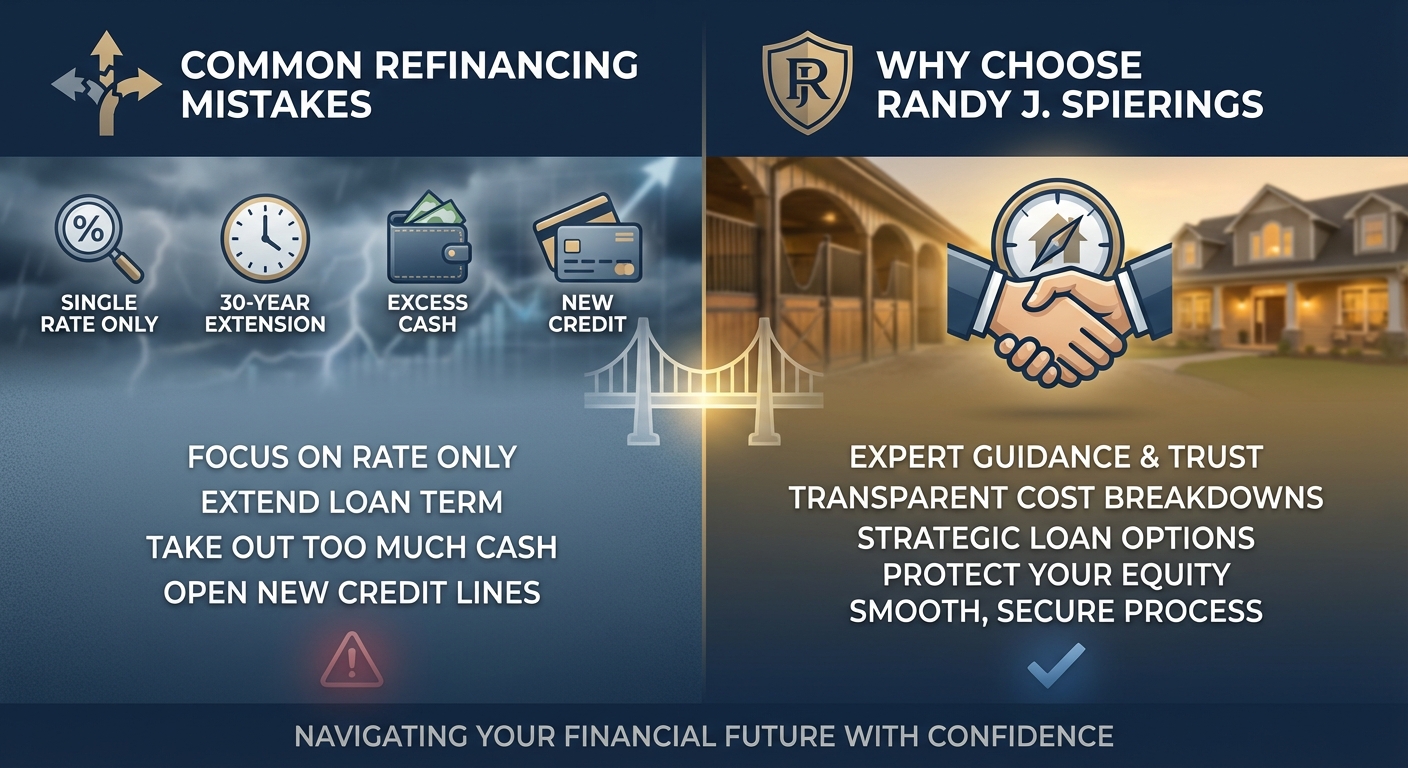
  • Focusing Only on the Interest Rate: While the rate is important, the APR (Annual Percentage Rate) and the closing costs are equally critical. Randy provides transparent breakdowns of all costs so you know exactly what you are paying and what your break-even point will be.
  • Extending the Loan Term Unnecessarily: If you are 10 years into a 30-year mortgage and you refinance into a new 30-year mortgage, you are extending your debt timeline and will likely pay more interest over the long run. Randy can help you explore 20-year or 15-year options to keep you on track.
  • Taking Out Too Much Cash: While it is tempting to pull out maximum equity during a cash-out refinance, it is vital to leave a healthy equity cushion in your home to protect against future market downturns.
  • Opening New Credit Lines During the Process: Applying for new credit cards or auto loans while your refinance is in underwriting can alter your debt-to-income ratio and potentially derail your loan approval. Always wait until your refinance is fully closed and funded.

Why Choose Randy J. Spierings at Primary Residential Mortgage, Inc.?

When it comes to your home and your financial future, who you work with matters. Here is why Greenwood Village homeowners trust Randy Spierings with their mortgage needs:

  • Local Greenwood Village Expertise: Randy understands the nuances of the Arapahoe County real estate market. From luxury jumbo loans in Cherry Hills Village and Greenwood Village to conventional financing across the Denver Metro, local knowledge ensures accurate appraisals and smooth closings.
  • Backed by a National Leader: As part of Primary Residential Mortgage, Inc. (PRMI), Randy has access to a vast portfolio of loan products, highly competitive rates, and robust in-house underwriting resources. You get the personalized service of a local broker with the power and stability of a national lender.
  • Transparent Communication: No hidden fees, no last-minute surprises, and no confusing mortgage jargon. Randy prides himself on educating his clients, ensuring you understand every number on your Loan Estimate and Closing Disclosure.
  • Customized Financial Strategies: Randy does not just quote rates; he builds financial strategies. He looks at your mortgage as a key component of your overall wealth-building plan.

Ready to get started?


Frequently Asked Questions

How much does it cost to refinance a mortgage?

Refinancing typically costs between 2% and 5% of the total loan amount. These closing costs cover the appraisal, title search, origination fees, and other administrative expenses. However, Randy Spierings can often structure your loan to roll these costs into the new mortgage balance or offer a “no-closing-cost” refinance by adjusting the interest rate, meaning you bring little to no cash to the closing table.

The break-even point is the time it takes for your monthly savings to exceed the costs of refinancing. For example, if your closing costs are $3,000 and your new mortgage saves you $150 per month, your break-even point is 20 months. If you plan to stay in your home longer than 20 months, refinancing is a sound financial decision.

While excellent credit secures the best interest rates, there are refinancing options available for homeowners with less-than-perfect credit. FHA and VA streamline refinances, for example, have very forgiving credit requirements. Randy can review your specific situation and advise you on the best path forward, or help you create a plan to improve your credit score before applying.

No, you are not obligated to refinance with your current mortgage servicer. In fact, shopping around is highly recommended. By working with Randy at PRMI, you can explore a wide variety of competitive options that your current lender may not offer.

On average, a mortgage refinance takes between 30 to 45 days from application to closing. Streamline refinances (FHA and VA) can often be completed much faster because they do not require a new appraisal or extensive income verification.

Yes. While the guidelines and interest rates for investment properties differ from primary residences, refinancing a rental property can be an excellent way to increase your monthly cash flow or pull out equity to purchase additional real estate. Randy Spierings is highly experienced in structuring investment property loans.

Estimate Your Monthly Payments

Understanding your potential mortgage payments is a crucial step in the home-buying process. Our easy-to-use Mortgage Calculator helps you estimate your monthly payments, so you can plan your finances with confidence. Simply enter your loan details and let our calculator do the rest.

mortgage
Primary Residential Mortgage, Inc. logo

PRMI NMLS 3094. PRMI is an Equal Housing Lender. Credit and collateral are subject to approval. Terms and conditions apply. Programs, rates, terms and conditions are subject to change and are subject to borrower(s) qualification. This is not a commitment to lend. The content in this website has not been approved, reviewed, sponsored or endorsed by any department or government agency.

Equal Housing Lender Logo
Customer satisfaction badge